India’s electronics industry is growing rapidly, but the most important question is not how many devices roll off assembly lines. It is how much of their technology, components and value India can produce at home.
A remarkable manufacturing expansion
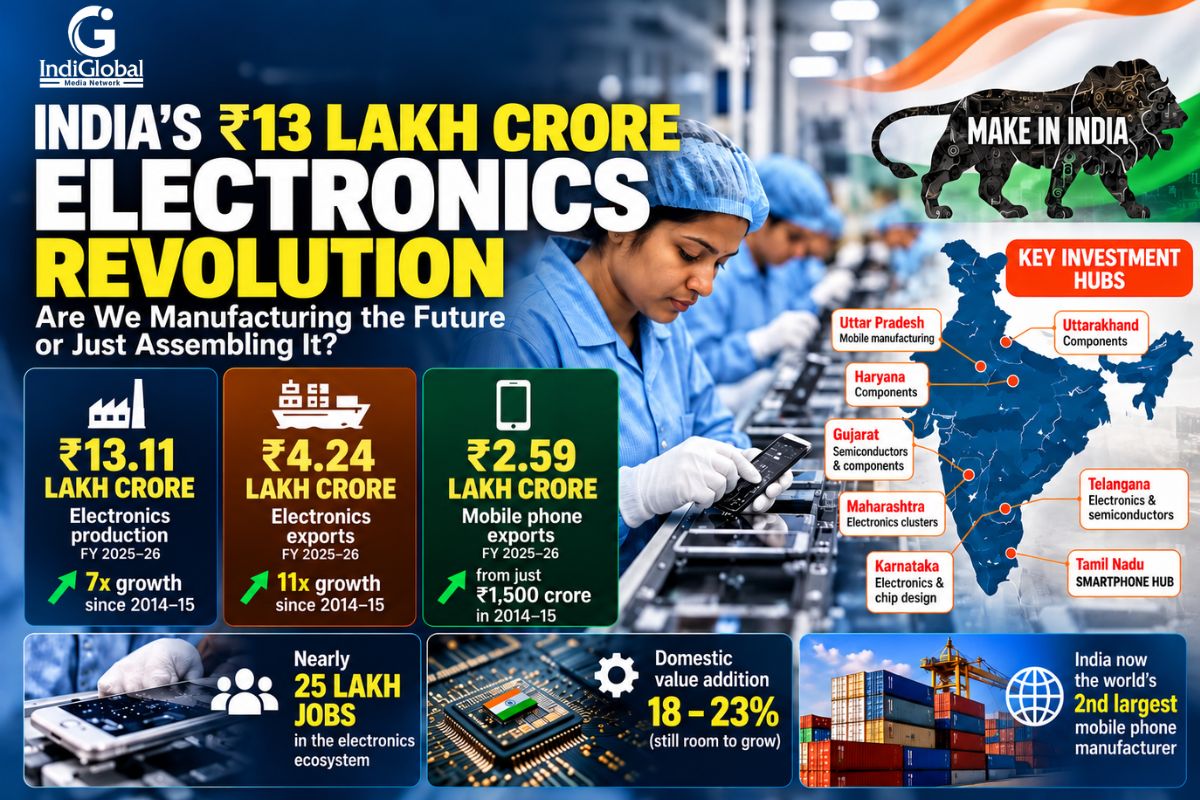
India’s electronics production reached approximately ₹13.11 lakh crore in FY 2025–26, compared with about ₹1.9 lakh crore in FY 2014–15. Electronics exports reached roughly ₹4.24 lakh crore, while mobile phone exports alone were around ₹2.59 lakh crore. These figures show how decisively the country has moved into global electronics supply chains.
Smartphone factories are visible evidence of the change. Yet a phone assembled in India can still contain imported chips, displays, camera sensors and other high-value components. That is why assembly growth and domestic technology capability must be assessed separately.
The next challenge: more value created in India
Domestic value addition has been estimated at roughly 18 to 23 percent in recent government reporting, though the measure varies by product and reporting period. Increasing that share means developing component suppliers, precision manufacturing, testing facilities, original designs and stronger research capabilities. It also means supporting smaller firms that supply larger manufacturers.
Where the investments and jobs are emerging
Electronics and semiconductor activity is spread across several states. Tamil Nadu is a major smartphone and electronics manufacturing centre; Karnataka combines electronics production with chip design; Uttar Pradesh has a substantial mobile manufacturing cluster around Noida; Gujarat is developing major semiconductor projects; and Telangana, Maharashtra, Haryana and Uttarakhand are participating in component manufacturing growth.
The Electronics Components Manufacturing Scheme had approved 106 projects involving proposed investments of ₹69,548 crore as of August 2026, with projected employment of 74,628 direct jobs and approximately 2.5 lakh indirect jobs across 15 states. These are project commitments and employment projections, not a verified tally of investments spent or jobs already filled.
State-wise manufacturing landscape
|
State |
Major activity |
Investment and employment status |
|
Tamil Nadu |
Smartphones, assembly and components |
No comparable statewide realised investment/job total verified |
|
Karnataka |
Electronics, design and industrial technology |
No comparable statewide realised investment/job total verified |
|
Uttar Pradesh |
Mobile phones and components, Noida cluster |
State policy target: about 4 lakh jobs; not achieved employment |
|
Gujarat |
Semiconductors and advanced electronics |
Large project announcements; use project-level figures |
|
Telangana |
Electronics, design and components |
New component project activity; statewide total not verified |
|
Maharashtra |
Electronics clusters and components |
Statewide total not verified |
|
Haryana |
Components manufacturing |
Statewide total not verified |
|
Uttarakhand |
Electronics components |
Statewide total not verified |
Why this matters to young Indians
Beyond export earnings, electronics growth can create careers in embedded systems, automation, quality engineering, industrial maintenance, chip design and supply-chain management. Government estimates suggest the wider electronics ecosystem supports nearly 25 lakh jobs, but future opportunities will depend on how successfully investment proposals become operating factories and how employers develop skilled roles.
The real measure of success
India has demonstrated that it can manufacture electronics at scale. The next test is whether it can make more of the components, develop more of the intellectual property and sustain competitive businesses over time. The country’s electronics revolution will be measured not just in rupees of output, but in the technology it creates and the quality of employment it supports.
Editorial data note
Production and export figures refer to FY 2025–26. ECMS investment and job figures are approvals and projections reported as of August 2026. State-specific realised investment and employment figures should not be inferred from national totals. Feature graphic is illustrative; map callouts indicate industry hubs, not measured state rankings.